


Close Menu
    • Top Fintech Startups in Switzerland
    • Switzerland Fintech Startup List
    • Virtual Banking
    • Open Banking
    • Online Mortgage
    • Regtech
    • Fintech Events
    • Submit Press Release
    • Submit Startup
    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • Media Kit
    • Contact Us
    • Work With Us
    • Newsletter
    • Submit Press Release
    • Submit Startup
    • Impressum
    Fintech Schweiz Digital Finance News – FintechNewsCH
    part of Fintech News Network

    Fintech News Network

    Facebook LinkedIn X (Twitter) Instagram RSS
    Free Newsletter
    • Blockchain
    • Wealthtech
    • Lending
    • Mobile Payments
    • Insurtech
    • PFM
    • AI
    • Funding
    • Various
      1. Germany
      2. London
      3. USA
      4. Austria
      5. Liechtenstein
      6. View All

      BaFin Fines Deutsche Bank €8 Million Over Postbank Migration Issues

      November 13, 2026

      Affirm Acquires Ratepay as Nexi Focuses on Core Activities

      November 10, 2026

      Eurex Clearing to Handle Digital and Traditional Assets Together

      November 4, 2026

      Deutsche Börse Extends Access to DAX 40 Stocks Beyond Xetra Hours

      October 28, 2026

      Payhawk Reaches US$2 Billion Valuation in Goldman Sachs-Led Series C

      November 20, 2026

      Griffin Raises US$20M to Add Card and Stablecoin Services

      November 13, 2026

      HSBC UK Launches Stripe-Powered Tap to Pay for Small Businesses

      November 12, 2026

      UBS Job Cuts Hit London as Credit Suisse Integration Enters Final Phase

      November 6, 2026

      Lauren Boyman Joins Broadridge from KPMG as Marketing Chief

      November 19, 2026

      Beacon Bank Taps Finastra to Simplify Payments After Its Merger

      November 17, 2026

      Wise Expands into US Investing via Its Broker-Dealer Licence

      November 16, 2026

      Anchorage Digital and Visa Add USDPT as a Settlement Option

      November 13, 2026

      Revolut Austria Banking Branch to Launch in 2027 With Local IBANs

      November 5, 2026

      BingX EU Secures MiCA Licence for Crypto Services in Europe

      October 15, 2026

      Bitget Pauses Withdrawals Following US$351.6M Hot Wallet Hack

      September 25, 2026

      Bybit Payments Secures Austria EMI License for European Payment Services

      August 5, 2026

      Swiss and Liechtenstein Banks Resist Core Banking System Overhaul

      November 11, 2026

      Swiss Blockchain Survey 2026: Banks on Stablecoins and Tokenized Funds

      October 20, 2026

      Bank Frick Enables Real-Time Euro Transfers and CHF Payment Receipts

      July 21, 2026

      Celsion Bank Begins Operations, Combining Digital Assets and Traditional Banking

      April 10, 2026

      Lauren Boyman Joins Broadridge from KPMG as Marketing Chief

      November 19, 2026

      Top Finfluencers in Switzerland in 2026

      November 10, 2026

      88% of Tech Founders Walk Away with Zero Exit Value

      November 9, 2026

      MUFG Bank Europe Absorbs Securities Arm to Become EU Universal Bank

      November 4, 2026
    • More
      • Fintech Events
      • Top Swiss Fintechs in 2026
      • Swiss Fintech Startup List
      • Accelerators
    Fintech Schweiz Digital Finance News – FintechNewsCH

    Fintech News Network

    Home»Payments»3 Archetypes of Instant Payment Adoption
    Payments

    3 Archetypes of Instant Payment Adoption

    In some markets, like India and Brazil, instant payments have reshaped the payment ecosystem, prompting banks to develop new revenue streams and payment card providers to strengthen their value proposition with premium products and new technologies.
    Fintechnews SwitzerlandFintechnews SwitzerlandAugust 31, 20265 Mins Read
    LinkedIn Facebook Twitter Telegram Copy Link Email
    3 Archetypes of Instant Payment Adoption
    Share
    Facebook Twitter LinkedIn Telegram Copy Link Email
    Free Newsletter

    Get the hottest Fintech Switzerland News once a month in your Inbox

    Across the world, the adoption of instant payments has varied significantly from one market to another, influenced less by the availability of real-time payment infrastructure and more by the broader payment ecosystem.

    Global consultancy McKinsey and Company identifies three main archetypes of instant payment adoption patterns that impact the payment value chain differently.

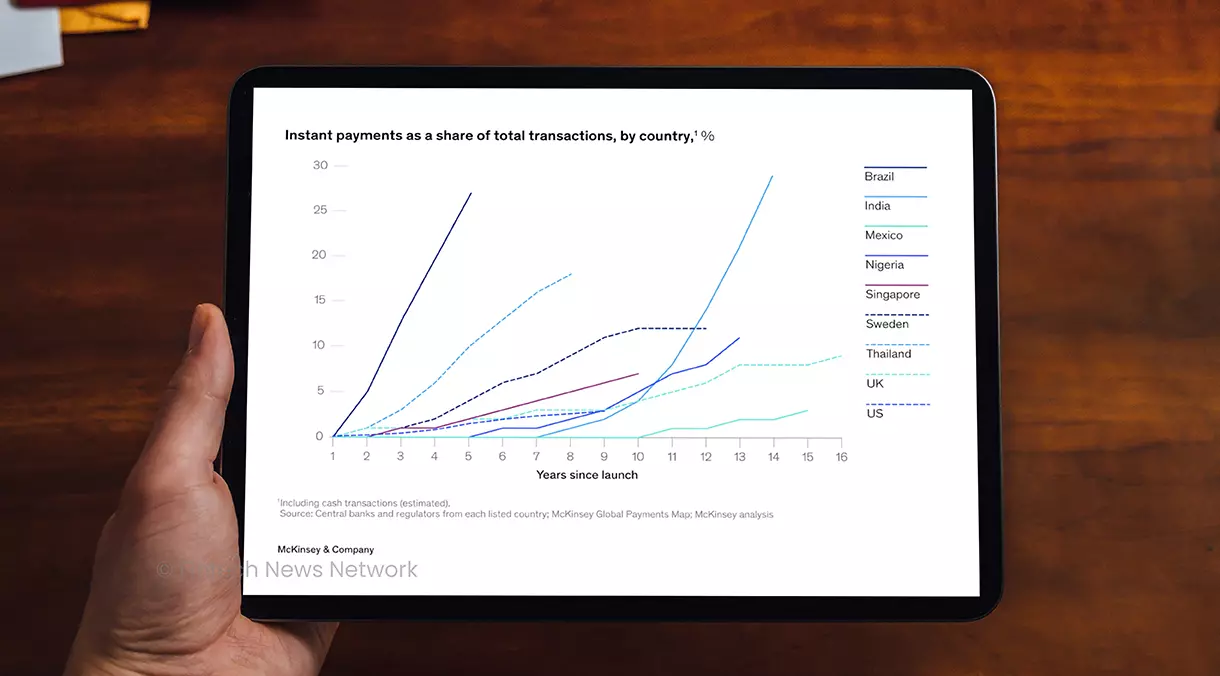
    The first archetype involves instant payments becoming the primary payment rail. In markets like India and Brazil, instant payments have fundamentally reshaped the payment ecosystem, effectively displacing cash, reducing debit card usage, and beginning to compete with credit cards in selected use cases.

    Bottomline

    In 2010, India launched the Immediate Payment Service (IMPS), an instant payment inter-bank electronic funds transfer system. This was followed in 2016 by the Unified Payments Interface (UPI), an instant mobile payment system that links multiple bank accounts into a single smartphone application.

    Since its launch, UPI has grown into the largest instant payment system in the world, processing more than 20 billion transactions per month, or nearly a third of India’s total transaction volume, according to McKinsey. It now accounts for 85% of India’s digital payment volume.

    Brazil, meanwhile, introduced its Pix system in 2020. Since its inception, instant payments have surged to account for nearly 30% of the country’s total transaction volume, with Pix now handling nearly 8 billion monthly transactions. Over 170 million consumers now use Pix, according to the country’s central bank, representing more than 90% of Brazil’s adult population.

    Impact on the payment value chain

    In markets like these where instant payments have reached mainstream adoption, banks, acquirers, and payment schemes have swiftly adapted to the transformation.

    Banks are using instant payments to strengthen customer relationships while developing new revenue streams. In Brazil, for example, several banks have introduced Pix Parcelado, which offers installment payments and credit offerings to customers on Brazil’s Pix instant payment network. This allows traditional lenders to preserve an important source of lending revenue. In India, while banks have embraced UPI for everyday payments, they are now differentiating themselves through lending, merchant solutions, and premium card offerings, McKinsey notes.

    Acquirers, meanwhile, have expanded beyond payment acceptance to become broader merchant technology providers, focusing now on software, analytics, financing, and other value-added services that help merchants better manage and grow their businesses. For example, the acquisition of Ravelin, an artificial intelligence (AI) fraud prevention platform, by payment firm Worldpay in 2025 exemplified this trend. This acquisition allowed Worldpay to add merchant fraud capabilities to its payment acceptance platform.

    Finally, card schemes have reinforced the value proposition through premium products, tokenization, fraud prevention, and digital-identity capabilities, while expanding into adjacent parts of the payments ecosystem through acquisitions and partnerships. For example, Visa’s acquisition of Pismo, a cloud-native issuer processing and core banking platform, in 2024 has strengthened its cloud-native banking infrastructure capabilities, adding support and connectivity for emerging payment schemes and real-time payment networks for financial institution clients.

    Other archetypes of instant payment adoption

    The second archetype of instant payment adoption highlighted by McKinsey is the complementing of established payment ecosystems. In the UK and other European markets, for example, instant payments are enhancing account-to-account (A2A) transfers for consumers and businesses, while cards remain the preferred payment method at the point of sale. In these markets, instant payments have seen reasonable growth, now accounting for about 10% of retail payments.

    As adoption of instant payments continue to mature in these markets, attention is now shifting towards making national instant payment systems work together. In Europe, for example, the Instant Payments Regulation (IPR) requires banks and payment providers across the region to offer euro-denominated instant credit transfers 24/7 at a cost no higher than standard traditional bank transfers, and introduces verification of payee to reduce fraud. In the UK, the Faster Payments System (FPS) now includes Payment Originating Overseas, which enables international payments to clear through the local scheme.

    Finally, the third and last archetype involves instant payments competing with established payment habits. The US and Mexico exemplify this pattern, with customer adoption stalling despite advanced infrastructure in place.

    In the US, instant payments are competing with an ecosystem that already offers consumers and businesses a wide range of convenient payment options, including cards, electronic money transfers though the Automated Clearing House (ACH), digital wallets, and real-time P2P networks.

    The US operates two real-time payment networks: the Clearing House banking association’s RTP network, launched in 2017, and the Federal Reserve’s FedNow Service, launched in 2023. Despite investments and growing participation, adoption has progressed slowly. In 2025, RTP processed approximately 447 million transactions, while FedNow processed about 8 million transactions, according to McKinsey. This represents a negligible fraction of the 345 billion payment transactions recorded in the US annually.

    Mexico, meanwhile, has struggled to translate its Interbank Electronic Payment System (SPEI) infrastructure into broad adoption of retail instant payments. This is despite the government’s multiple attempts to spur adoption through the launch of initiatives such as Cobro Digital (CoDi), an instant payment platform built on top of SPEI introduced in 2019, and Dinero Móvil (DiMo), launched in 2023 to boost P2P transactions and overcome CoDi’s adoption challenges. Today, instant payments represent less than 5% of Mexico’s total transaction volume, according to McKinsey.

    Several factors contributed to the limited demand for instant payments in Mexico. These include continued reliance on cash, limited financial inclusion, and weak merchant adoption. Some research estimates that 90% of consumer transactions in Mexico are still performed in cash.

    Instant payments as a share of total transactions, by country, %, Source: McKinsey, Aug 2026
    Instant payments as a share of total transactions, by country, %, Source: McKinsey, Aug 2026


    Featured image: Edited by Fintech News Switzerland, based on image by Mohammad Ayoub via Magnific

    Sponsored ReportThe Payments Intelligence GapRead
    Instant Payments
    Share. Facebook LinkedIn Twitter Telegram Copy Link Email

    Author

    fintech switzerland
    Fintechnews Switzerland
    • Facebook
    • X (Twitter)

    Related Posts

    Tether Backs SCRYPT as It Expands into Stablecoin Payments

    November 20, 2026

    Payhawk Reaches US$2 Billion Valuation in Goldman Sachs-Led Series C

    November 20, 2026

    Rivero’s Amiko Goes Live at SIX for Debit Card Fraud and Dispute Claims

    November 19, 2026

    Beacon Bank Taps Finastra to Simplify Payments After Its Merger

    November 17, 2026

    Wealthsimple Offers Tetra’s CADD to Beta Clients

    November 16, 2026

    Wise Expands into US Investing via Its Broker-Dealer Licence

    November 16, 2026

    CrediBill Suspends Service After Cyberattack Amid Signs of Data Theft

    November 16, 2026

    Anchorage Digital and Visa Add USDPT as a Settlement Option

    November 13, 2026
    AI Sponsored

    81% of Financial Firms Use AI. Only 14% Call It Transformational

    October 21, 2026
    Fintech Newsletter
    Subscribe to the most important Fintech Switzerland News
    Follow Us
    • Facebook
    • X / Twitter
    • LinkedIn
    • Instagram
    Swiss Fintech Startup Directory

    Swiss Fintech Startup Directory

    Top Swiss Fintech Startups

    Top Fintech Startups in Switzerland for 2026

    Upcoming Fintech Events
    Country
    AI & Big Data Expo Global 2027
    February 3, 2027
    -
    February 4, 2027
    United Kingdom
    -
    London
    Digital Finance Summit 2026
    December 3, 2026
    Belgium
    -
    Brussels
    Digital Society 2026
    November 25, 2026
    Germany
    -
    Frankfurt am Main
    FIBE Berlin 2027
    April 7, 2027
    -
    April 8, 2027
    Germany
    -
    Berlin
    FINANZ 2027
    March 17, 2027
    -
    March 18, 2027
    Switzerland
    -
    Zurich
    Promote Event View More
    Whitepapers & E-Books
    The Future of Competitive Advantage in Banking & Payments
    The Future of Competitive Advantage in Banking & Payments
    Bottomline
    American Newsletter

    Fintech News America

    Australia Fintech Map

    Australia Fintech Map

    Philippines Fintech Report

    SINGAPORE FINTECH REPORT

    Singapore Fintech Map 2025

    Indonesia Fintech Report

    Indonesia Fintech Map 2025 banner

    UAE Fintech Report

    UAE Fintech Report 2024

    Free Business Accounts

    Navigation
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    Other Fintech News Network Publications
    Fintech News Switzerland
    Fintech News Singapore
    Fintech News Malaysia
    Fintech News Hong Kong
    Fintech News Philippines
    Fintech News Network Indonesia
    Fintech News Network Australia
    Fintech News Baltic
    Fintech News Nordics
    Fintech News America
    Fintech News UAE
    Fintech News Africa
    Get Informed

    Subscribe to Updates

    Subscribe to the most important Fintech Switzerland News

    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    © 2015 - 2026 Copyright CK Finanzpro GmbH. All Rights reserved.

    Type above and press Enter to search. Press Esc to cancel.

    Fintech Schweiz Digital Finance News - FintechNewsCH
    Manage Consent

    Your Privacy Matters to Us

    To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
