


Close Menu
    • Top Fintech Startups in Switzerland
    • Switzerland Fintech Startup List
    • Virtual Banking
    • Open Banking
    • Online Mortgage
    • Regtech
    • Fintech Events
    • Submit Press Release
    • Submit Startup
    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • Media Kit
    • Contact Us
    • Work With Us
    • Newsletter
    • Submit Press Release
    • Submit Startup
    • Impressum
    Fintech Schweiz Digital Finance News – FintechNewsCH
    part of Fintech News Network

    Fintech News Network

    Facebook LinkedIn X (Twitter) Instagram RSS
    Free Newsletter
    • Blockchain
    • Wealthtech
    • Lending
    • Mobile Payments
    • Insurtech
    • PFM
    • AI
    • Funding
    • Various
      1. Germany
      2. London
      3. USA
      4. Austria
      5. Liechtenstein
      6. View All

      BaFin Fines Deutsche Bank €8 Million Over Postbank Migration Issues

      November 13, 2026

      Affirm Acquires Ratepay as Nexi Focuses on Core Activities

      November 10, 2026

      Eurex Clearing to Handle Digital and Traditional Assets Together

      November 4, 2026

      Deutsche Börse Extends Access to DAX 40 Stocks Beyond Xetra Hours

      October 28, 2026

      Griffin Raises US$20M to Add Card and Stablecoin Services

      November 13, 2026

      HSBC UK Launches Stripe-Powered Tap to Pay for Small Businesses

      November 12, 2026

      UBS Job Cuts Hit London as Credit Suisse Integration Enters Final Phase

      November 6, 2026

      Monzo Weighs New Funding at £7.5 Billion Valuation as Buyout Talks Stall

      November 6, 2026

      Beacon Bank Taps Finastra to Simplify Payments After Its Merger

      November 17, 2026

      Wise Expands into US Investing via Its Broker-Dealer Licence

      November 16, 2026

      Anchorage Digital and Visa Add USDPT as a Settlement Option

      November 13, 2026

      Swiss Wealthtech Firm Avaloq Expands Into US Market

      November 11, 2026

      Revolut Austria Banking Branch to Launch in 2027 With Local IBANs

      November 5, 2026

      BingX EU Secures MiCA Licence for Crypto Services in Europe

      October 15, 2026

      Bitget Pauses Withdrawals Following US$351.6M Hot Wallet Hack

      September 25, 2026

      Bybit Payments Secures Austria EMI License for European Payment Services

      August 5, 2026

      Swiss and Liechtenstein Banks Resist Core Banking System Overhaul

      November 11, 2026

      Swiss Blockchain Survey 2026: Banks on Stablecoins and Tokenized Funds

      October 20, 2026

      Bank Frick Enables Real-Time Euro Transfers and CHF Payment Receipts

      July 21, 2026

      Celsion Bank Begins Operations, Combining Digital Assets and Traditional Banking

      April 10, 2026

      Top Finfluencers in Switzerland in 2026

      November 10, 2026

      88% of Tech Founders Walk Away with Zero Exit Value

      November 9, 2026

      MUFG Bank Europe Absorbs Securities Arm to Become EU Universal Bank

      November 4, 2026

      Swiss Officials Weigh the Costs of a UBS Relocation Abroad

      October 30, 2026
    • More
      • Fintech Events
      • Top Swiss Fintechs in 2026
      • Swiss Fintech Startup List
      • Accelerators
    Fintech Schweiz Digital Finance News – FintechNewsCH

    Fintech News Network

    Home»AI»How Neobanks and AI Are Breaking Customer Loyalty in Banking — Insights from McKinsey
    AI Blockchain Virtual Banking

    How Neobanks and AI Are Breaking Customer Loyalty in Banking — Insights from McKinsey

    Banking incumbents are losing their customer grip, as fintech firms and neobanks expand, and as the adoption of AI and stablecoin accelerates, according to McKinsey.
    Fintechnews SwitzerlandFintechnews SwitzerlandJune 16, 20266 Mins Read
    LinkedIn Facebook Twitter Telegram Copy Link Email
    Fintech, Neobanks, AI Erode Client Loyalty to Traditional Banks
    Share
    Facebook Twitter LinkedIn Telegram Copy Link Email
    Free Newsletter

    Get the hottest Fintech Switzerland News once a month in your Inbox

    In the past 20 years, many analysts and banking leaders predicted banks would lose their hold on customers. Some foresaw this after the 2008 financial crisis, others during the 2010s explosive growth of technology platform companies and the first wave of fintech startups.

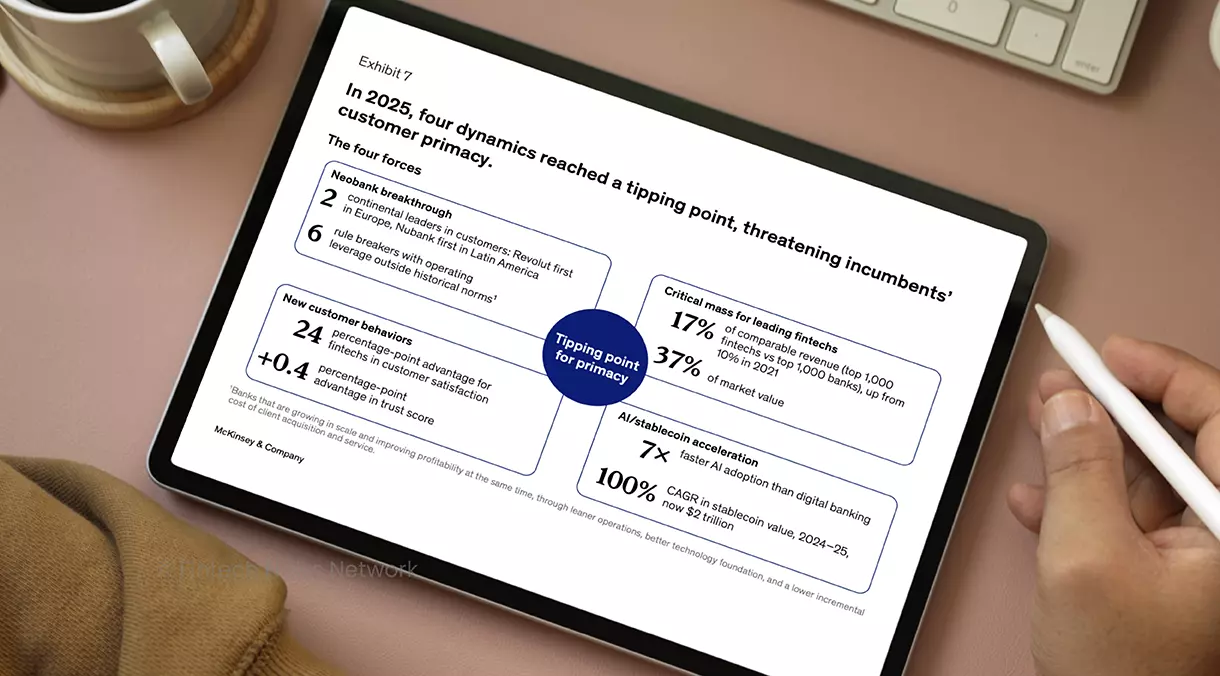
    Despite all these predictions, the tipping point where banks truly lost customer grip didn’t actually happen until 2025. This turning point was propelled by transformative changes across four key dimensions: the maturation of fintech firms, evolving customer behaviors, breakthroughs in neobanking, and the accelerated adoption of artificial intelligence (AI) and stablecoins, according to McKinsey’s 2026 Global Banking Annual Review.

    Four dynamics reached a tipping point in 2025, threatening incumbents' customer primacy, Source: 2026 Global Banking Annual Review, McKinsey, May 2026
    Four dynamics reached a tipping point in 2025, threatening incumbents’ customer primacy, Source: 2026 Global Banking Annual Review, McKinsey, May 2026

    Fintech firms evolve and mature

    The report, released in May 2026, analyzes the global banking sector’s 2025 performance, profitability trends, and strategic direction for financial institutions. This edition highlights a tipping point in customer relationship, catalyzed in part by the evolution of the fintech ecosystem.

    Bottomline

    In 2025, fintech revenues reached US$650 billion. While this remains a small portion of the banking industry’s US$7.3 trillion, the sector has matured significantly, with established firms reaching scale, and using their capital to attack some of banking’s most valuable profit pools, particularly in payments, wealth management, capital markets, and lending.

    A comparison of the world’s top 1,000 banks versus the top 1,000 fintech firms further highlights this trend. The “millenniad” of the top banks generated US$3.8 trillion in revenues, while their fintech counterparts generated US$625 billion. These figures represent a 22% increase between 2021 and 2025 for fintech firms, compared to just 5% for banks.

    Looking ahead, fintech firms are set for further expansion as several reversed their strategy and are now actively pursuing banking licenses. In 2025, 21 banking license applications were filed in the US, marking a sharp increase from one in 2024 and five in 2023. About 38% of these applications were accepted.

    Neobanking booms

    Similarly, leading neobanks continued to grow in 2025, achieving scale at unprecedented speeds across major markets. As of December 2025, UK-based Revolut was the 11th-most-valuable bank in Europe, and now boasts 75 million retail customers. Nubank claims 135 million customers, and is the most valuable bank in Latin America. For China’s WeBank, the figures are 430 million customers and 11th place in market value among the nation’s banks.

    Financially, these institutions outperform incumbents on several key metrics. While the return on equity (ROE) for the US and European banking industries sits at about 12%, Nubank’s is at about 30%, Robinhood’s exceeds 20%, and Revolut and Wise both clock in at about 35%.

    Higher ROE for neobanks means they are generating more profit from every dollar of shareholder investment compared to traditional banks. This advantage largely comes from their lean business models, which avoids expensive physical branches and outdated technology systems.

    Leading banks, by number of customers and ROE, 2021-2025, Source: 2026 Global Banking Annual Review, McKinsey, May 2026
    Leading banks, by number of customers and ROE, 2021-2025, Source: 2026 Global Banking Annual Review, McKinsey, May 2026

    As established neobanks grow, these players continue to expand their suite of banking products and services. Nubank launched in 2014 its first product, a no-fee credit card, and now offers current and savings accounts, debit cards, money transfer, and services for businesses.

    Revolut, which launched in 2015 with prepaid cards, foreign exchange, and spending analytics, today offers about 50 products, including capital markets, commodities, and crypto trading; personal loans; a range of credit cards; and a suite of services for small and medium-size enterprises (SMEs).

    Agentic AI and stablecoins are dissolving customer stickiness

    AI agents and stablecoins represent two emerging technologies that threaten to erode the relationship between traditional banks and their customers.

    AI agents can perform task and solve issues largely on its own. In deposits, they can monitor balances in real time, compare returns across institutions, sweep idle cash into higher-yield accounts, and then sweep cash back to a checking account in time for bills. This not only reduces customers’ reliance on traditional banks, but also allows more of the spreads captured by banks to go to account holders, effectively cutting off some of the revenue banks earn from passive accounts.

    Beyond deposits, AI agents can help consumers shift credit card balances, exploit sign-up offers, and cash in loyalty points. They can also make tax planning simple for consumers and might provide an entry point into wealth management and advisory. Consumer lending and other banking businesses could also lose customers to agent-powered fintech solutions.

    Stablecoins is another technology that poses a similar threat to the customer relationship. Stablecoins can make it cheaper and faster to send money across borders, which is particularly valuable for uses such as trade finance or remittances involving jurisdictions with less developed payments systems. As adoption of stablecoins grows, fiat deposits may shift toward stablecoin reserves, and businesses may reduce cash buffers required for international operations.

    The stablecoins market has grown from less than US$10 billion six years ago to more than US$300 billion today. Citi estimates this figure could reach up to US$4 trillion by 2030.

    Shifting customer behaviors

    Finally, the fourth and last driver highlighted by McKinsey is the fundamental shift in customer behavior. Traditional banks have historically relied on older customers for an outsize share of revenues and profits. That’s becoming a problem as younger customers are revealing quite different preferences for how they want to bank. These customers are more highly engaged, expect services that put the customer at the center, value innovation, and prize responsiveness.

    Incumbents oftentimes struggle to deliver these qualities, prompting younger customers to consider switching to nonbank providers. According to a 2025 Deloitte survey, younger consumers are significantly more willing to switch banks. Specifically, 26.6% of Gen Z and 22.5% of Millennial respondents, born between 1981 and 2012, indicated they are likely to switch within the next two years. This rate is two to five times higher than that of their Gen X or Baby Boomer counterparts, born between 1946 and 1980.

    Percentage of respondents who are likely to switch in the next two years, Source: Deloitte Consumer Banking 2025 Survey, Feb 2026
    Percentage of respondents who are likely to switch in the next two years, Source: Deloitte Consumer Banking 2025 Survey, Feb 2026

    In terms of digital platform usage, Millennials lead across most categories, though Gen Z track closely behind, except for payments, where Gen X, millennial, and Gen Z respondents exhibit a similar level of preference.

    Percentages of respondents using selected financial apps, Source: Deloitte Consumer Banking 2025 Survey, Feb 2026
    Percentages of respondents using selected financial apps, Source: Deloitte Consumer Banking 2025 Survey, Feb 2026


    Featured image: Edited by Fintech News Switzerland, based on image by thanyakij-12 via Magnific

    Sponsored ReportThe Payments Intelligence GapRead
    banking client loyalty Fintech neobanking stablecoin
    Share. Facebook LinkedIn Twitter Telegram Copy Link Email

    Author

    fintech switzerland
    Fintechnews Switzerland
    • Facebook
    • X (Twitter)

    Related Posts

    Fintech Marketers Adapt As AI-Powered Search Reshapes Brand Discovery

    November 17, 2026

    Milan Court Orders Year-Long Oversight of Revolut in Italy

    November 17, 2026

    Swiss Banking Trade Association Calls for Regulatory Push on Domestic Stablecoins

    November 17, 2026

    Nubank to Gain Banking Licence in Brazil through Bank Acquisition

    November 16, 2026

    Wealthsimple Offers Tetra’s CADD to Beta Clients

    November 16, 2026

    Anchorage Digital and Visa Add USDPT as a Settlement Option

    November 13, 2026

    Griffin Raises US$20M to Add Card and Stablecoin Services

    November 13, 2026

    Sygnum Fund Aims to Grow Investors’ ETH Beyond Staking

    November 13, 2026
    AI Sponsored

    81% of Financial Firms Use AI. Only 14% Call It Transformational

    October 21, 2026
    Fintech Newsletter
    Subscribe to the most important Fintech Switzerland News
    Follow Us
    • Facebook
    • X / Twitter
    • LinkedIn
    • Instagram
    Swiss Fintech Startup Directory

    Swiss Fintech Startup Directory

    Top Swiss Fintech Startups

    Top Fintech Startups in Switzerland for 2026

    Upcoming Fintech Events
    Country
    AI & Big Data Expo Global 2027
    February 3, 2027
    -
    February 4, 2027
    United Kingdom
    -
    London
    Digital Finance Summit 2026
    December 3, 2026
    Belgium
    -
    Brussels
    Digital Society 2026
    November 25, 2026
    Germany
    -
    Frankfurt am Main
    EURO FINANCE Tech Day 2026
    November 18, 2026
    Germany
    -
    Frankfurt
    European Digital Finance Conference 2026
    November 19, 2026
    Netherlands
    -
    Amsterdam
    Promote Event View More
    Whitepapers & E-Books
    The Future of Competitive Advantage in Banking & Payments
    The Future of Competitive Advantage in Banking & Payments
    Bottomline
    American Newsletter

    Fintech News America

    Australia Fintech Map

    Australia Fintech Map

    Philippines Fintech Report

    SINGAPORE FINTECH REPORT

    Singapore Fintech Map 2025

    Indonesia Fintech Report

    Indonesia Fintech Map 2025 banner

    UAE Fintech Report

    UAE Fintech Report 2024

    Free Business Accounts

    Navigation
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    Other Fintech News Network Publications
    Fintech News Switzerland
    Fintech News Singapore
    Fintech News Malaysia
    Fintech News Hong Kong
    Fintech News Philippines
    Fintech News Network Indonesia
    Fintech News Network Australia
    Fintech News Baltic
    Fintech News Nordics
    Fintech News America
    Fintech News UAE
    Fintech News Africa
    Get Informed

    Subscribe to Updates

    Subscribe to the most important Fintech Switzerland News

    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    © 2015 - 2026 Copyright CK Finanzpro GmbH. All Rights reserved.

    Type above and press Enter to search. Press Esc to cancel.

    Fintech Schweiz Digital Finance News - FintechNewsCH
    Manage Consent

    Your Privacy Matters to Us

    To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
