


Close Menu
    • Top Fintech Startups in Switzerland
    • Switzerland Fintech Startup List
    • Virtual Banking
    • Open Banking
    • Online Mortgage
    • Regtech
    • Fintech Events
    • Submit Press Release
    • Submit Startup
    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • Media Kit
    • Contact Us
    • Work With Us
    • Newsletter
    • Submit Press Release
    • Submit Startup
    • Impressum
    Fintech Schweiz Digital Finance News – FintechNewsCH
    part of Fintech News Network

    Fintech News Network

    Facebook LinkedIn X (Twitter) Instagram RSS
    Free Newsletter
    • Blockchain
    • Wealthtech
    • Lending
    • Mobile Payments
    • Insurtech
    • PFM
    • AI
    • Funding
    • Various
      1. Germany
      2. London
      3. USA
      4. Austria
      5. Liechtenstein
      6. View All

      BaFin Fines Deutsche Bank €8 Million Over Postbank Migration Issues

      November 13, 2026

      Affirm Acquires Ratepay as Nexi Focuses on Core Activities

      November 10, 2026

      Eurex Clearing to Handle Digital and Traditional Assets Together

      November 4, 2026

      Deutsche Börse Extends Access to DAX 40 Stocks Beyond Xetra Hours

      October 28, 2026

      Griffin Raises US$20M to Add Card and Stablecoin Services

      November 13, 2026

      HSBC UK Launches Stripe-Powered Tap to Pay for Small Businesses

      November 12, 2026

      UBS Job Cuts Hit London as Credit Suisse Integration Enters Final Phase

      November 6, 2026

      Monzo Weighs New Funding at £7.5 Billion Valuation as Buyout Talks Stall

      November 6, 2026

      Beacon Bank Taps Finastra to Simplify Payments After Its Merger

      November 17, 2026

      Wise Expands into US Investing via Its Broker-Dealer Licence

      November 16, 2026

      Anchorage Digital and Visa Add USDPT as a Settlement Option

      November 13, 2026

      Swiss Wealthtech Firm Avaloq Expands Into US Market

      November 11, 2026

      Revolut Austria Banking Branch to Launch in 2027 With Local IBANs

      November 5, 2026

      BingX EU Secures MiCA Licence for Crypto Services in Europe

      October 15, 2026

      Bitget Pauses Withdrawals Following US$351.6M Hot Wallet Hack

      September 25, 2026

      Bybit Payments Secures Austria EMI License for European Payment Services

      August 5, 2026

      Swiss and Liechtenstein Banks Resist Core Banking System Overhaul

      November 11, 2026

      Swiss Blockchain Survey 2026: Banks on Stablecoins and Tokenized Funds

      October 20, 2026

      Bank Frick Enables Real-Time Euro Transfers and CHF Payment Receipts

      July 21, 2026

      Celsion Bank Begins Operations, Combining Digital Assets and Traditional Banking

      April 10, 2026

      Top Finfluencers in Switzerland in 2026

      November 10, 2026

      88% of Tech Founders Walk Away with Zero Exit Value

      November 9, 2026

      MUFG Bank Europe Absorbs Securities Arm to Become EU Universal Bank

      November 4, 2026

      Swiss Officials Weigh the Costs of a UBS Relocation Abroad

      October 30, 2026
    • More
      • Fintech Events
      • Top Swiss Fintechs in 2026
      • Swiss Fintech Startup List
      • Accelerators
    Fintech Schweiz Digital Finance News – FintechNewsCH

    Fintech News Network

    Home»Money Transfer»Switzerland Sets the Stage for Instant Payments
    Money Transfer Payments Sponsored

    Switzerland Sets the Stage for Instant Payments

    Vitus Rotzer, Chief Product Officer - Financial Messaging, BottomlineVitus Rotzer, Chief Product Officer - Financial Messaging, BottomlineNovember 28, 20228 Mins Read
    LinkedIn Facebook Twitter Telegram Copy Link Email
    Switzerland Sets the Stage for Instant Payments
    Share
    Facebook Twitter LinkedIn Telegram Copy Link Email
    Free Newsletter

    Get the hottest Fintech Switzerland News once a month in your Inbox

    Stability. Secrecy. Safety. The Swiss financial system has been the very definition of these attributes for almost 200 years. But like the world’s financial systems, institutions and networks, one very active new factor is knocking at the border: change. And the Swiss are up to it. Let’s take a look at the main factors that are bringing change to business payments in Switzerland detailed in a recent report commissioned by Bottomline from analyst firm Aite-Novarica.

    The report covers payment infrastructure changes across a large geography of Europe and, also the UK. Specific to Switzerland, it validates the following major areas that I believe will be the most important to the country as it straddles the line between its independent status and its ability to take inspiration from other global initiatives.

    1. The importance of interoperability to ensure the Swiss marketplace can have ubiquity with the global economy, especially their close neighbours in Europe.

    2. The drive to modernise domestic payments (Instant Payments, RTGS) by ensuring a state-of-the-art and innovative marketplace.

    3. Although Switzerland is in front of the curve when it comes to ISO 20022 (since 2015), further steps are needed to move towards ISO Native to comply with SWIFT’s CBPR+ standard for cross-border payments to ensure the aforementioned interoperability

    4. Keeping abreast of the security within transactions such as fraud protection, sanctions screening, IBAN pre-validation etc.
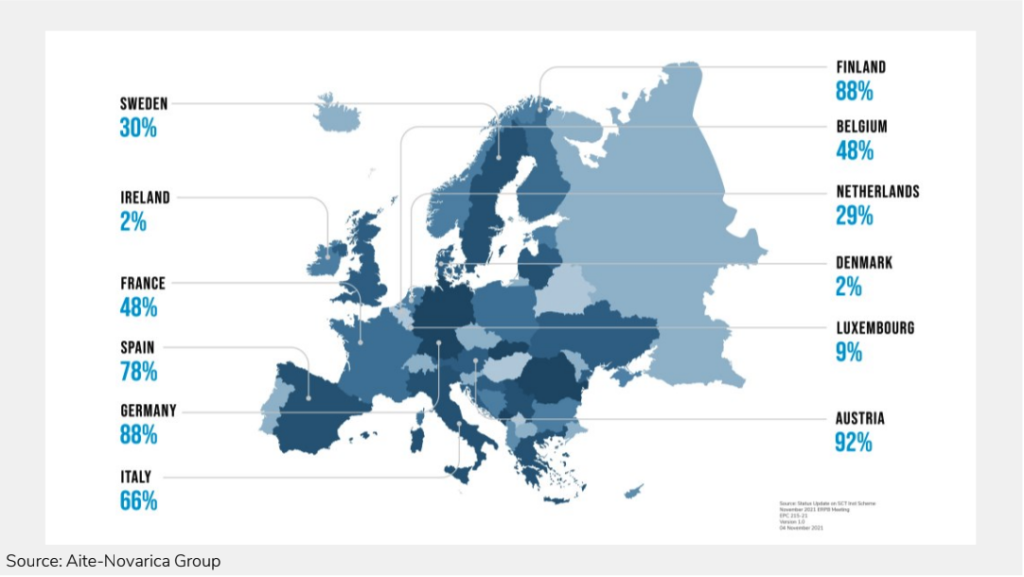
    SCT INST PARTICIPATION RATES, 2022
    SCT INST PARTICIPATION RATES, 2022

    Instant Payments are ‘table-stakes’

    Instant payments, in my opinion, are the most positive development for the Swiss financial sector in years due to their proven role as a catalyst for change within that system. Instant payments are mainly used for domestic purposes, rather than cross-border and hold the promise of providing Switzerland with a competitive and innovative marketplace where citizens and SMEs can leverage the speed for improved liquidity and enriched data for transparency. Led by the Swiss National Bank (SNB) and SIX, Switzerland will introduce instant payments starting in 2024. It is proof positive that the country is committed to digital payments transformation, even as its citizens show the classic tendency to use cash. “Instant payments,” says the Aite-Novarica report, “are becoming the norm.” 

    Deadlines and more deadlines

    SIC has mandated two key deadlines: being reachable via SIC Instant Payment will be mandatory by August 2024 for banks processing more than 500,000 SIC messages annually and will be mandatory for the rest of the marketplace by August 2026. Now, all this will not happen automatically. As stated before, infrastructure upgrades are needed. However, the emphasis should be on reducing the complexity by outsourcing these changes to very specialised third-party providers. This strategy will also help with speed-to-market and ensure ongoing compliance with new industry mandates and regulations. 

    This is even more important right now in the face of the legislative proposal by the European Union to make instant payments in euros available to all citizens and businesses holding a bank account in the EU and EEA countries. This according to Reuters is in response to only 11% of euro credit transfers being in the form of instant payments at the end of 2021.  PSPs would have six months to be ready to receive instant payments in euros in the euro area and 12 months for sending instant payments in euros. 

    How does this impact Switzerland?  It’s complicated. Switzerland is not part of the EU and seems to be playing both sides of the SEPA issue – as it should. 

    I quote Dieter Goerdten, head of products and services at SIX, which is the banking consortium that operates the SIC platform.

    “Switzerland is a small economy compared to its European neighbours,”

    he told the European Payments Council.

    “It is dependent on trade and easy access to the European markets. Seamless payment flows are an essential part of this easy access. It is therefore always of keen interest to all parts of the Swiss economy to ensure a close alignment with European payment standards. Consequently, Switzerland is a member of SEPA and continues to implement digital payments based on SEPA rules wherever possible.”

    Instant payments are also about competitive advantage, and now that the EU Commission has on the 26th of October issued their mandatory regulation for Instant Payments in Euros – which will still need to legally enter into force before being compulsory, you don’t want to be in a situation in the rest of the world where you’re playing catch-up. That alone should move instant payments up the priority ladder. Secondly, instant payments represent a revenue opportunity that will only grow as banks find new ways to leverage it. Thirdly, instant payments are a springboard for digital payments transformation and are quite simply ‘table-stakes’ – If you don’t offer it to end customers and corporates then they are more than likely going to rethink their relationships with your financial institution and switch. 

    Managing interoperability

    Feedback from the banks gathered at Sibos was that because they have very busy roadmaps there is a real need for banks & financial institutions to be supported by centralised platforms to help with speed, simplification, cost and hitting deadlines. After all, interoperability doesn’t work if some banks are moving at different speeds.

    Banks that attended Sibos, and I hope every financial institution in Switzerland, are aware that although the situation is currently in flux, it won’t be for long. They recognised that you cannot just wait and that some legacy systems are not fit for the revolution that is coming. ISO 20022 is the sharp tip of the spear in achieving this interoperability. It’s one standard that works across countries and networks despite there being some variations case by case. We have now also seen ambitious deadlines for ISO 20022 and instant payment capabilities being pushed back (Target 2, SWIFT CBPR+, Canada’s Lynx to March 2023 and the Bank of England is likely to follow suit in the UK too), in response to banks being worried about juggling deadlines within an already busy roadmap. But to be clear the message from SWIFT at Sibos was that even if changing key dates brings a bit of confusion, the emphasis should be on getting the implementation right straight off the bat, rather than rushing the process which could result in potential problems further down the line.  

    However, the view at Sibos, and also held by Bottomline, is that the sooner you can fully leverage the advantages of ISO 20022 the better. This should take the form of implementing ISO in several steps. Firstly, ensuring compliance and using translation services where necessary. Secondly, ensure that you are fully leveraging and managing the rich data that will be available through ISO by being able to manage truncations. And lastly, make the full transition to ISO Native where ISO 20022 is integrated across your whole payments ecosystem and you can reap the rewards of optimum operational efficiency.  After all, ISO 20022 is designed to ensure that elusive full end-to-end automation by being the only 100% machine-readable format, allowing banks & FIs to reduce costs and any risks related to manual interventions. 

    We aren’t fully aware of all the use cases for ISO 20022 and we won’t find them all out until we have integrated ISO fully, started brainstorming and had a play around. The sooner you start exploring these new use cases the sooner you can gain a competitive advantage over other banks. However, the wider benefits that we do know include – high-levels of transparency, better customer service, and of course, improved operational efficiency.

    After all, ISO 20022 provides the standardisation needed for interoperability between traditional domestic & cross-border rails. It is also vital for the adoption of new innovative payment rails for cross-border and instant payments because all of these have transitioned to ISO 20022 too. In addition, the abundant availability of rich data and related (artificial) intelligence will allow banks & FIs to route payments intelligently and to choose the right channel for each transaction, whether it is to drive new coverage in markets or currencies or to optimise the execution in existing markets. In my opinion, the impact that the richer data will have on fraud monitoring & compliance, cash-flow management and of course data and analytics, justifies enough for the fastest transition to being ISO Native and having ISO front and centre of any bank’s roadmap. 

    I’ll end with a telling quote from the Aite-Novarica report:

    “Despite the strong regulatory mandate of the ECB (European Central Bank) and the EU’s appetite for SEPA harmonisation, maintaining a competitive position remains a central plank of policy making. As such, multiple systems will likely continue to exist simultaneously highlighting the need for of course connectivity, but interoperability too.”

    To read the Europe & UK wide Bottomline sponsored Aite Noverica report European Payments Infrastructure Under Renovation – Impact in Financial Institutions in full click here. Additionally, you can also find the report that is specific to Switzerland and Liechtenstein.
    bottomline payment banner

    Featured image credit: Edited from Unsplash here and here

    Aite-Novarica Group Bottomline Technologies
    Share. Facebook LinkedIn Twitter Telegram Copy Link Email

    Author

    Vitus Rotzer
    Vitus Rotzer, Chief Product Officer - Financial Messaging, Bottomline

    Vitus Rotzer is the Chief Product Officer - Financial Messaging Global at Bottomline. Vitus is leading the strategy to expand Bottomline’s business globally. Vitus is a versatile senior executive with strong leadership, management, and business development skills. He has over 20 years’ experience in financial services and software technology within leading and international companies, encompassing sales management and senior executive roles.

    Related Posts

    Beacon Bank Taps Finastra to Simplify Payments After Its Merger

    November 17, 2026

    Wealthsimple Offers Tetra’s CADD to Beta Clients

    November 16, 2026

    Wise Expands into US Investing via Its Broker-Dealer Licence

    November 16, 2026

    CrediBill Suspends Service After Cyberattack Amid Signs of Data Theft

    November 16, 2026

    Anchorage Digital and Visa Add USDPT as a Settlement Option

    November 13, 2026

    EBANX and Eneba See Payment Volume Rise 138% in Latin America

    November 13, 2026

    HSBC UK Launches Stripe-Powered Tap to Pay for Small Businesses

    November 12, 2026

    Affirm Acquires Ratepay as Nexi Focuses on Core Activities

    November 10, 2026
    AI Sponsored

    81% of Financial Firms Use AI. Only 14% Call It Transformational

    October 21, 2026
    Fintech Newsletter
    Subscribe to the most important Fintech Switzerland News
    Follow Us
    • Facebook
    • X / Twitter
    • LinkedIn
    • Instagram
    Swiss Fintech Startup Directory

    Swiss Fintech Startup Directory

    Top Swiss Fintech Startups

    Top Fintech Startups in Switzerland for 2026

    Upcoming Fintech Events
    Country
    AI & Big Data Expo Global 2027
    February 3, 2027
    -
    February 4, 2027
    United Kingdom
    -
    London
    Digital Finance Summit 2026
    December 3, 2026
    Belgium
    -
    Brussels
    Digital Society 2026
    November 25, 2026
    Germany
    -
    Frankfurt am Main
    European Digital Finance Conference 2026
    November 19, 2026
    Netherlands
    -
    Amsterdam
    FIBE Berlin 2027
    April 7, 2027
    -
    April 8, 2027
    Germany
    -
    Berlin
    Promote Event View More
    Whitepapers & E-Books
    The Future of Competitive Advantage in Banking & Payments
    The Future of Competitive Advantage in Banking & Payments
    Bottomline
    American Newsletter

    Fintech News America

    Australia Fintech Map

    Australia Fintech Map

    Philippines Fintech Report

    SINGAPORE FINTECH REPORT

    Singapore Fintech Map 2025

    Indonesia Fintech Report

    Indonesia Fintech Map 2025 banner

    UAE Fintech Report

    UAE Fintech Report 2024

    Free Business Accounts

    Navigation
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    Other Fintech News Network Publications
    Fintech News Switzerland
    Fintech News Singapore
    Fintech News Malaysia
    Fintech News Hong Kong
    Fintech News Philippines
    Fintech News Network Indonesia
    Fintech News Network Australia
    Fintech News Baltic
    Fintech News Nordics
    Fintech News America
    Fintech News UAE
    Fintech News Africa
    Get Informed

    Subscribe to Updates

    Subscribe to the most important Fintech Switzerland News

    Facebook LinkedIn X (Twitter) Instagram RSS
    • About Fintech News Network
    • FNN Media Kit
    • Work With Us
    • Contact Us
    • Fintech Switzerland Newsletter
    • Submit Press Release
    • Submit Fintech Startup
    • Datenschutzerklärung / Impressum
    © 2015 - 2026 Copyright CK Finanzpro GmbH. All Rights reserved.

    Type above and press Enter to search. Press Esc to cancel.

    Fintech Schweiz Digital Finance News - FintechNewsCH
    Manage Consent

    Your Privacy Matters to Us

    To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.

    Functional Always active
    The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
    Preferences
    The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
    Statistics
    The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
    Marketing
    The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
    • Manage options
    • Manage services
    • Manage {vendor_count} vendors
    • Read more about these purposes
    View preferences
    • {title}
    • {title}
    • {title}
